The people who funded your company first are almost always the people who know the least about it. Your Series A lead has a board seat, a side letter with information rights, and a partner whose job is to read your monthly numbers. Your aunt, your college roommate, and the angel who wrote a $50,000 check off a fifteen-minute conversation have none of that. They have a signature page, a wire confirmation, and whatever you choose to tell them.
That asymmetry is the whole problem. The investors with the fewest contractual protections took the most risk, and they are the ones most likely to be left in the dark. Most founders don’t do this maliciously. Updates get skipped during a hard quarter, then skipped again because the first skip made the second one awkward, and eighteen months later there is no communication habit left to resume. By then the damage is not just reputational. It is structural, and it shows up precisely when the company can least afford it.
Silence Does Not Read as Neutral
An investor who hears nothing does not conclude that things are fine. They conclude that things are bad and that you don’t want to say so. This is not paranoia; it is a reasonable inference, because founders who are hitting their numbers tend to talk about it. As an angel investor myself, I know how this feels and it’s not a good feeling when you’ve put your trust in an entrepreneur.
The information vacuum gets filled with something, and what fills it is usually worse than the truth. A missed quarter, explained in three sentences with a plan attached, is a data point. That same missed quarter, discovered two years later when the company is raising a down round, is a revelation, and it retroactively recolors every prior month of silence as concealment.
A quarterly cadence is the floor, not the goal. Quarterly is frequent enough that no single update has to carry catastrophic news, and infrequent enough that a busy founder can actually sustain it. Monthly is better if you can hold the line. What matters more than frequency is consistency: an update that arrives every quarter without fail, even when the news is flat, builds a kind of credibility that no amount of eloquence in a crisis can substitute for.
What Actually Belongs in One
Founders overbuild these documents and then stop sending them because they take a full day to produce. Keep it to a page. Cash in the bank and months of runway. Revenue or whatever your two or three real metrics are, shown against the prior quarter. What went well, stated briefly. What went badly, stated more briefly and without hedging. Key hires and departures. Anything that materially changed the plan. And a specific ask, because your investors are a distribution network for introductions, candidates, and customers, and most of them would help if they knew how.
Be careful with forward-looking statements and projections, and think about whether anything you’re sharing is material nonpublic information that constrains what recipients can do. But do
not let the fear of saying something imprecise become an excuse to say nothing. The legal exposure from a candid, appropriately caveated update is far smaller than the exposure from a two-year silence followed by an urgent request for a signature. Work with your lawyer and have him or her review the update before you send it out if you are concerned about what information you are sharing.
The Fundraising Consequences Are Concrete
This is where the soft issue becomes a hard one.
Follow-on capital dries up first. Angels and friends-and-family investors are a meaningful source of bridge financing, and they are frequently the only source available when the round is not coming together. Nobody bridges a company they haven’t heard from. The check you need in month twenty-two depends on the update you sent in month four.
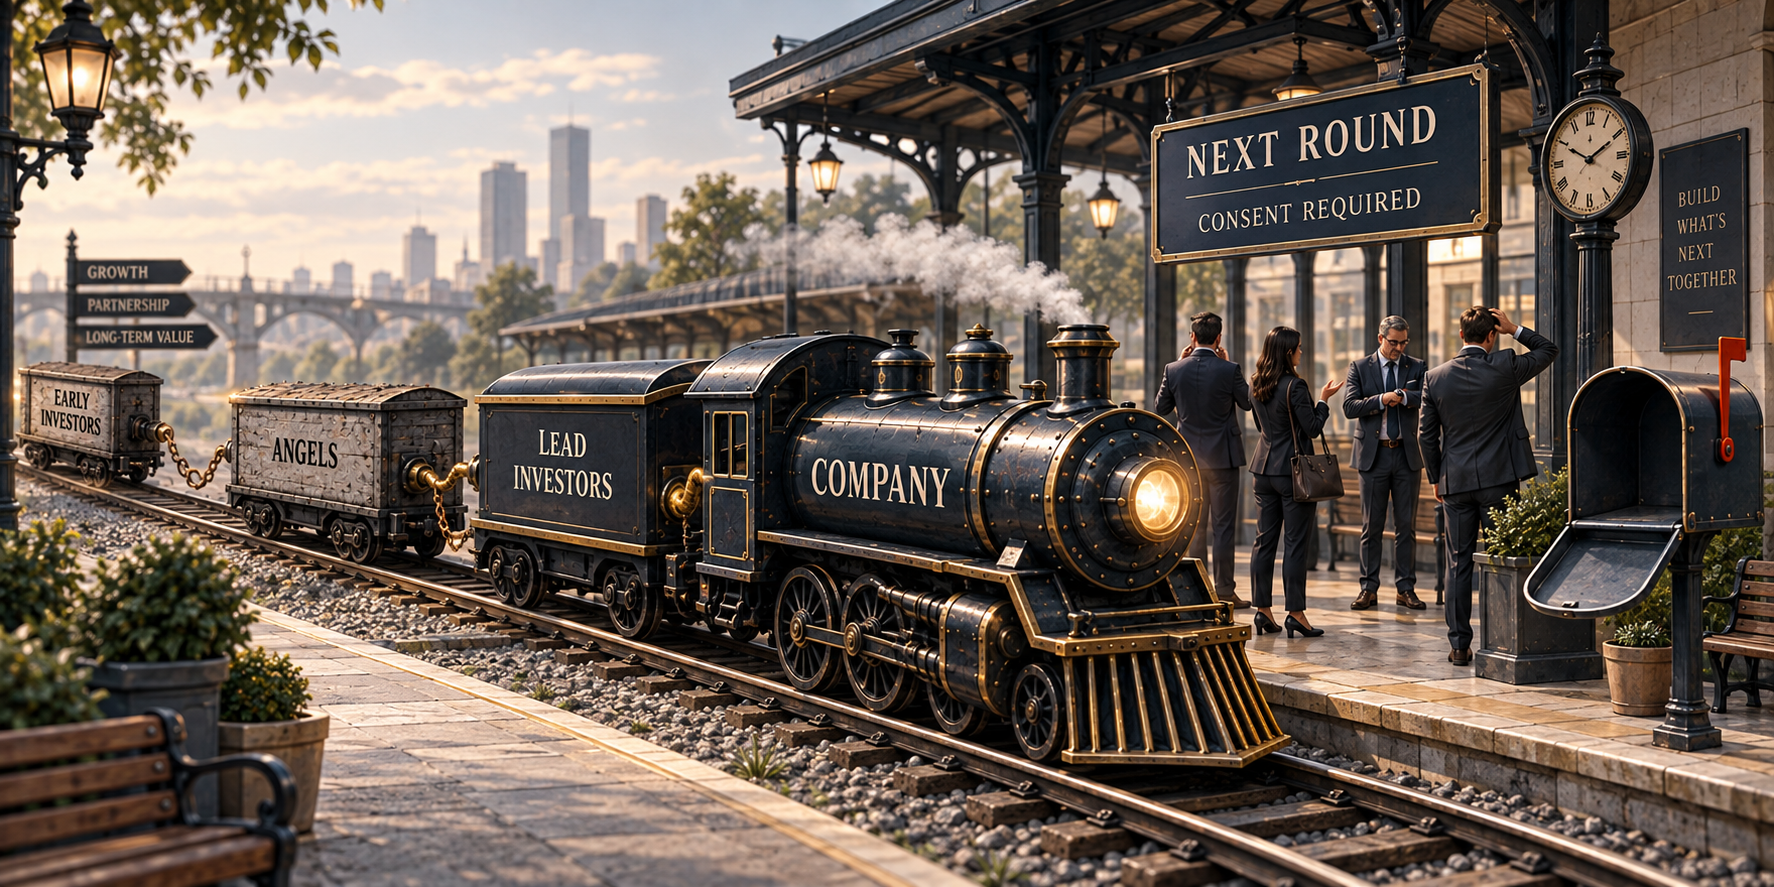
You will eventually need their signatures. Most financings require stockholder approval to amend the charter, increase authorized shares, or create a new senior series. Amending outstanding Safes or convertible notes typically requires the consent of a majority in interest of the holders. If your early investors collectively hold a meaningful block, you are not asking a friendly group for a routine approval. You are asking people who feel forgotten to sign a document that helps someone else. Holdouts have leverage, they know it, and even a small group can push a closing past the point where the lead’s patience runs out.
Bad terms plus no relationship is a combustible mix. Down rounds, pay-to-play provisions, recapitalizations, aggressive participating preferred, and reverse splits that compress the common stock all fall hardest on the earliest money. An investor who has watched the runway shrink quarter by quarter generally understands why the terms look the way they do; they may not like it, but they can follow the logic. An investor whose first substantive communication in two years is a consent solicitation explaining that their position is being reduced by eighty-five percent hears something entirely different. They hear that they were kept quiet until their consent was needed. That is the conversation that produces refusals, demands for information under the books-and-records statute, breach-of-fiduciary-duty claims, and occasionally a disclosure schedule item that kills a deal.
Diligence surfaces all of it. New lead investors ask about cap table hygiene. They ask whether prior rounds were properly authorized, whether consents were obtained, whether any holder has threatened a claim. Unsigned consents, an unhappy holder with a lawyer, or a pending information demand each translate into extended timelines, additional reps and warranties, indemnity carve-outs, or a reduced valuation. A relationship problem becomes a diligence problem becomes a price problem.
Treat It as Part of the Capital Structure
The practical fix is unglamorous. Build one template and reuse it. Pick a date on the calendar and honor it. Use a single channel so nobody is guessing where the news lives. Send it even when there is nothing good to say, and especially then. Loop in counsel on the specific disclosures that carry legal weight, but do not turn a one-page letter into a registration statement.
Founders tend to think of investor updates as a courtesy owed to people who were kind enough to believe early. They are better understood as maintenance on an asset. The willingness of your existing holders to fund you again, to sign what you put in front of them, and to give you the benefit of the doubt when the terms are ugly is a real asset, and it depreciates in silence.